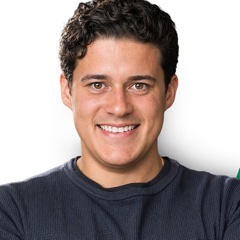
Luis Andino
Founder and CEO of Ditch
Where to hear and read about Luis Andino1 episode or test

Luis Andino is the founder and CEO of Ditch, an app that automates debt repayment through roundups, and a former LendingPoint lender who saw heavy debt come from following the default path. The thing most worth learning from him is to prove people will pay and that unit economics work before scaling, then pour fuel on growth.
You can't expect that the first action that the user does is a debit because there is no balance.
How Ditch Hit $3M ARR by Automating Debt Repayment
Luis Andino: the story and the lessons
1How Luis Andino came to build Ditch
Andino saw at LendingPoint that heavy debt follows the default path. He expected $25,000 personal loans at 30% APR to trace back to bad decisions. He instead found people doing what society expects, reaching about $70,000 of debt before a first financial mistake.
He left LendingPoint in 2023 to build Ditch. His framing is that wealth building once ran from 0 to 1 and now runs from negative one to zero.
Ditch launched as an exploratory product built to measure intent. The first version was a canvas instrumented to track every user action, and features sat behind buttons so Ditch could count taps before building anything. It only built what pulled.
Roundups pointed at debt beat everything else tested, so Ditch pivoted in May 2024. Andino describes the app as an "intent radar" and an "intent magnet".
Roundups aimed at debt borrow Acorns' mechanic for a more urgent problem. A $4.50 coffee sends a 50 cent roundup to a student loan, credit card or mortgage. Andino calls debt a "way more contemporary" problem than saving.
The idea was to deliver progress without asking users to do anything.
Growth sped up sharply after the pivot. The first $1M of ARR took two years, the next $1M took 80 days, and the third took 59 days. Sixteen days after hitting $3M, Ditch was approaching $4M.
Ditch's real user is not the one Andino assumed. The average user is a 29-year-old woman, 70% of users are women, and many are nurses, doctors, consultants or tech workers. They hold mid to high interest student loans, credit cards, personal loans and BNPL.
Andino says "the desire to pay off debt faster doesn't have to equate incredibly high credit utilization." Roundups are not meant for someone with $100,000 of credit card debt, and other features are in development for heavier debt.
2Andino's rules for proving the business before scaling
Andino used a hard paywall to test whether the product mattered. Ditch was venture-backed from day one and could have chased users first. Andino feared that path would mean never building something people pay for, so he made the paywall the litmus test.
He warns that a 60 to 70% trial conversion means little if the price is too low, because the tests must be rebuilt at the right price.
Ditch spent two years on onboarding, activation and retention first. The question for the first two years was how to build a product a user would want to pay for. Proving payback at small scale gave Ditch permission to find capital and deploy it on growth.
Once payback is short, Andino says founders should spend more. He calls scaling a responsibility once unit economics work, since the goal is a ubiquitous brand.
Andino delivers value passively because users will not self-serve. People who need financial help rarely want education, and an app cannot out-compete the dopamine of social media. Ditch asks for one decision in about 10 minutes of onboarding, then lets progress compound.
His goal was "a tool that automated progress so that it felt inevitable." He says budgeting and net worth apps mostly attract people who don't need them.
Andino right-sized payoff goals after pushing maximums caused churn. Ditch first pushed users to pay as much as possible, which drove them away. A model now sets the recommended payoff from linked checking accounts and credit cards.
His example: onboarding promises $1,000 a month and week one sends $250, then by week two the user panics because they needed the money. Gamification still rewards extra payments.
3How Ditch scores and tests onboarding
Ditch treats each onboarding screen as a credit or a debit. Screens asking for a name, email or date of birth subtract from the balance. Unless the ad impression is very strong, the first action cannot be a debit.
Ditch assigns point values to experiences, which sets how large a debit can follow. This builds on Darius Contractor's Psych framework from Dropbox, with measured data added.
Ditch simulates a roundup in onboarding as its biggest credit. The user imagines a $3.50 coffee, taps complete purchase in a bottom sheet labeled as a simulation, and watches the roundup travel to their debt. A celebration animation ends it.
Ditch measured this as a large credit, say 100 points on an arbitrary scale. Only after it does the flow ask for account creation or a trial start.
Ditch removes screens one at a time to measure their value. Removal A/B tests show how trial start rate and trial conversion change. If nothing changes, the screen goes.
A longer onboarding first lifted trial start and conversion strongly over the earlier frictionless flow. Andino notes that years of only adding steps would end in a bloated flow.
Six or seven pre-paywall screens argue the subscription pays for itself. They are personalized to the debt the user entered. Because Ditch is a financial product, it measures ROI as interest saved on extra payments the user would not otherwise make.
Saved interest is benchmarked against the subscription and fees Ditch charges. Andino notes even affluent users resist subscription fees.
4Andino's organic to paid content playbook
Andino tested and disproved the advice that organic content fails as paid. Expert media buyers and app founders told him organic winners would not work as paid. Ditch started with a TikTok UGC program because it costs least to enter, then ran the best videos as Spark ads.
The test ladder went from optimizing for impressions, to installs, to trials. The same videos then went to Meta, where the worst case was a few hundred dollars of spend.
About 90% of Ditch's ad content comes from its UGC program. Winning formats include trending audio with product demos, talking heads and founder ads.
Because platforms keep changing auction rules, Ditch tests from first principles instead of following current doctrine.
Ditch adds a thin brand layer so repeat impressions compound. An in-house editor applies consistent text, edit style and overlays to each UGC video chosen for paid. Raw UGC differs in setting, creator, audio and on-screen text, so a second ad does not feel like the first.
Andino says peers spending seven and eight figures a month on paid ads found the idea useful.
Ditch puts about 80% of its ad budget on Meta. Andino calls Meta the best advertising network ever, because it pairs a profile with a relevant ad better than any network Ditch tested.
TikTok-style content still feels native there because the same people use Instagram and TikTok. He adds that the choice of conversion event decides how well Meta finds the right person.
5How Ditch makes money from a cost-sensitive audience
Ditch charges a fee only when the product delivers value. A processing fee applies only on payments actually made, so cost tracks the value users get. The average user pays 2.7x their base roundup amount against debt.
Andino says the fee was "a way for us to delegate some of the cost of using the product to when the product actually generated value for the user."
A subscription frees Ditch from pushing products that add no value. Mint, Rocket Money and Albert earn by referring users to credit cards, refinancing, consolidation and debt settlement. Ditch's fee reduces that pressure and lets it add offers only where they help.
Knowing how much surplus value it creates tells Ditch how to price. A refinance marketplace targets users overpaying interest on student loans, auto loans and credit cards.
6Where Andino expects Ditch to go next
Andino wants always-on agents that refinance debt in minutes. His example is an 8.5% student loan that could drop to 4% during a six-month window the borrower never notices. Agents could take a user from an offer to a signed refinance in minutes, possibly many times a year.
He argues sophisticated financial tools have been regressive, with more access the wealthier you are, and cheap AI changes that. He also floats "fluid credit", where lenders compete for the best rate.
Andino plans community and employer benefits to ease debt stigma. Many people do not think of student loans as debt, or think they need no help. Ditch plans community, challenges and gamification, citing a Wall Street Journal story that Americans are addicted to watching others pay off debt.
Employers could offer Ditch as a benefit because 401(k) participation is dipping while workers carry high-interest debt.
Paid acquisition has barely been scratched. Meta needs enough conversion events per week to learn, so a rare event today becomes frequent as budgets grow, allowing a sharper conversion event.
7How Andino builds the team and raises money
Andino now wants to hire ahead of growth instead of staying lean. He sees gaps in communication and growth operations that top hires should fill over the next few quarters. The more he sees the return on great people, the less he wants to stay lean.
He values working with engineers from MIT and Georgia Tech and solving problems together at a whiteboard. He says hiring from elite schools and from no school at all has shown him few patterns that predict success.
Andino asks of nearly every task whether an agent can do it. Agents are only as good as the time spent setting up connectors and skills. Team members who did not originate the idea turn against agents after the first mistake.
If a task can't be done by an agent, he sees possible alpha. He says this keeps each team member highly leveraged while staying lean.
Andino runs fundraising as a tight process that creates FOMO. Many VCs dislike consumer subscription apps and try to retrofit their own go-to-market ideas onto a founder. He advises a clear strategy with no founder half in and half out.
He compares it to dating: you are the hottest girl at the bar. He adds that not every company should chase venture-scale returns, so decide early and stay steadfast despite fund feedback.
Meeting a real user made the mission concrete for Andino. In early 2024, with about 700 users, a stranger on a New York train recognized his Ditch hat and said she loved the app.
He had assumed paying subscribers were family and friends. He also hears from single mothers who have paid off thousands of dollars of debt with Ditch.
How Ditch Hit $3M ARR by Automating Debt Repayment
Ditch pivoted from an exploratory AI debt companion to automated roundups for debt repayment, then spent two years perfecting unit economics before scaling. The episode explains the onboarding scoring, organic to paid content flywheel and value-based monetization behind its jump from $1M to nearly $4M ARR in about five months.
Andino saw at LendingPoint that heavy debt follows the default path. He expected $25,000 personal loans at 30% APR to trace back to bad decisions. He instead found people doing what society expects, reaching about $70,000 of debt before a first financial mistake.
He left LendingPoint in 2023 to build Ditch. His framing is that wealth building once ran from 0 to 1 and now runs from negative one to zero.
Ditch launched as an exploratory product built to measure intent. The first version was a canvas instrumented to track every user action, and features sat behind buttons so Ditch could count taps before building anything. It only built what pulled.
Roundups pointed at debt beat everything else tested, so Ditch pivoted in May 2024. Andino describes the app as an "intent radar" and an "intent magnet".
Roundups aimed at debt borrow Acorns' mechanic for a more urgent problem. A $4.50 coffee sends a 50 cent roundup to a student loan, credit card or mortgage. Andino calls debt a "way more contemporary" problem than saving.
The idea was to deliver progress without asking users to do anything.
Growth sped up sharply after the pivot. The first $1M of ARR took two years, the next $1M took 80 days, and the third took 59 days. Sixteen days after hitting $3M, Ditch was approaching $4M.
Ditch's real user is not the one Andino assumed. The average user is a 29-year-old woman, 70% of users are women, and many are nurses, doctors, consultants or tech workers. They hold mid to high interest student loans, credit cards, personal loans and BNPL.
Andino says "the desire to pay off debt faster doesn't have to equate incredibly high credit utilization." Roundups are not meant for someone with $100,000 of credit card debt, and other features are in development for heavier debt.
Andino used a hard paywall to test whether the product mattered. Ditch was venture-backed from day one and could have chased users first. Andino feared that path would mean never building something people pay for, so he made the paywall the litmus test.
He warns that a 60 to 70% trial conversion means little if the price is too low, because the tests must be rebuilt at the right price.
Ditch spent two years on onboarding, activation and retention first. The question for the first two years was how to build a product a user would want to pay for. Proving payback at small scale gave Ditch permission to find capital and deploy it on growth.
Once payback is short, Andino says founders should spend more. He calls scaling a responsibility once unit economics work, since the goal is a ubiquitous brand.
Andino delivers value passively because users will not self-serve. People who need financial help rarely want education, and an app cannot out-compete the dopamine of social media. Ditch asks for one decision in about 10 minutes of onboarding, then lets progress compound.
His goal was "a tool that automated progress so that it felt inevitable." He says budgeting and net worth apps mostly attract people who don't need them.
Andino right-sized payoff goals after pushing maximums caused churn. Ditch first pushed users to pay as much as possible, which drove them away. A model now sets the recommended payoff from linked checking accounts and credit cards.
His example: onboarding promises $1,000 a month and week one sends $250, then by week two the user panics because they needed the money. Gamification still rewards extra payments.
Ditch treats each onboarding screen as a credit or a debit. Screens asking for a name, email or date of birth subtract from the balance. Unless the ad impression is very strong, the first action cannot be a debit.
Ditch assigns point values to experiences, which sets how large a debit can follow. This builds on Darius Contractor's Psych framework from Dropbox, with measured data added.
Ditch simulates a roundup in onboarding as its biggest credit. The user imagines a $3.50 coffee, taps complete purchase in a bottom sheet labeled as a simulation, and watches the roundup travel to their debt. A celebration animation ends it.
Ditch measured this as a large credit, say 100 points on an arbitrary scale. Only after it does the flow ask for account creation or a trial start.
Ditch removes screens one at a time to measure their value. Removal A/B tests show how trial start rate and trial conversion change. If nothing changes, the screen goes.
A longer onboarding first lifted trial start and conversion strongly over the earlier frictionless flow. Andino notes that years of only adding steps would end in a bloated flow.
Six or seven pre-paywall screens argue the subscription pays for itself. They are personalized to the debt the user entered. Because Ditch is a financial product, it measures ROI as interest saved on extra payments the user would not otherwise make.
Saved interest is benchmarked against the subscription and fees Ditch charges. Andino notes even affluent users resist subscription fees.
Andino tested and disproved the advice that organic content fails as paid. Expert media buyers and app founders told him organic winners would not work as paid. Ditch started with a TikTok UGC program because it costs least to enter, then ran the best videos as Spark ads.
The test ladder went from optimizing for impressions, to installs, to trials. The same videos then went to Meta, where the worst case was a few hundred dollars of spend.
About 90% of Ditch's ad content comes from its UGC program. Winning formats include trending audio with product demos, talking heads and founder ads.
Because platforms keep changing auction rules, Ditch tests from first principles instead of following current doctrine.
Ditch adds a thin brand layer so repeat impressions compound. An in-house editor applies consistent text, edit style and overlays to each UGC video chosen for paid. Raw UGC differs in setting, creator, audio and on-screen text, so a second ad does not feel like the first.
Andino says peers spending seven and eight figures a month on paid ads found the idea useful.
Ditch puts about 80% of its ad budget on Meta. Andino calls Meta the best advertising network ever, because it pairs a profile with a relevant ad better than any network Ditch tested.
TikTok-style content still feels native there because the same people use Instagram and TikTok. He adds that the choice of conversion event decides how well Meta finds the right person.
Ditch charges a fee only when the product delivers value. A processing fee applies only on payments actually made, so cost tracks the value users get. The average user pays 2.7x their base roundup amount against debt.
Andino says the fee was "a way for us to delegate some of the cost of using the product to when the product actually generated value for the user."
A subscription frees Ditch from pushing products that add no value. Mint, Rocket Money and Albert earn by referring users to credit cards, refinancing, consolidation and debt settlement. Ditch's fee reduces that pressure and lets it add offers only where they help.
Knowing how much surplus value it creates tells Ditch how to price. A refinance marketplace targets users overpaying interest on student loans, auto loans and credit cards.
Andino wants always-on agents that refinance debt in minutes. His example is an 8.5% student loan that could drop to 4% during a six-month window the borrower never notices. Agents could take a user from an offer to a signed refinance in minutes, possibly many times a year.
He argues sophisticated financial tools have been regressive, with more access the wealthier you are, and cheap AI changes that. He also floats "fluid credit", where lenders compete for the best rate.
Andino plans community and employer benefits to ease debt stigma. Many people do not think of student loans as debt, or think they need no help. Ditch plans community, challenges and gamification, citing a Wall Street Journal story that Americans are addicted to watching others pay off debt.
Employers could offer Ditch as a benefit because 401(k) participation is dipping while workers carry high-interest debt.
Paid acquisition has barely been scratched. Meta needs enough conversion events per week to learn, so a rare event today becomes frequent as budgets grow, allowing a sharper conversion event.
Andino now wants to hire ahead of growth instead of staying lean. He sees gaps in communication and growth operations that top hires should fill over the next few quarters. The more he sees the return on great people, the less he wants to stay lean.
He values working with engineers from MIT and Georgia Tech and solving problems together at a whiteboard. He says hiring from elite schools and from no school at all has shown him few patterns that predict success.
Andino asks of nearly every task whether an agent can do it. Agents are only as good as the time spent setting up connectors and skills. Team members who did not originate the idea turn against agents after the first mistake.
If a task can't be done by an agent, he sees possible alpha. He says this keeps each team member highly leveraged while staying lean.
Andino runs fundraising as a tight process that creates FOMO. Many VCs dislike consumer subscription apps and try to retrofit their own go-to-market ideas onto a founder. He advises a clear strategy with no founder half in and half out.
He compares it to dating: you are the hottest girl at the bar. He adds that not every company should chase venture-scale returns, so decide early and stay steadfast despite fund feedback.
Meeting a real user made the mission concrete for Andino. In early 2024, with about 700 users, a stranger on a New York train recognized his Ditch hat and said she loved the app.
He had assumed paying subscribers were family and friends. He also hears from single mothers who have paid off thousands of dollars of debt with Ditch.