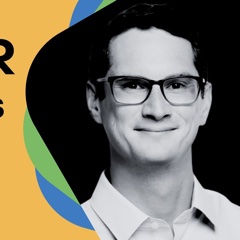
Andrew Maguire
Managing Partner at Volo Ventures; hosts from RevenueCat
Where to hear and read about Andrew Maguire1 episode or test

Andrew Maguire is Managing Partner at Volo Ventures. He has run a subscription app himself and now invests in consumer apps. The lesson most worth taking from him is to bootstrap a niche app and raise venture only if you can say how the company sells for a billion dollars.
There has never been a better time to indie developer a $10 million app.
The Bootstrapper's Path to $10M ARR Without Venture Capital – Andrew Maguire, Volo Ventures
Andrew Maguire: the story and the lessons
1Why Andrew Maguire says taste, not engineering, limits great apps
Maguire says product taste now limits how many great apps exist. Five years ago $20M could hire the best engineers, but without product intuition it was $20 million on fire. Today the cap on high-quality apps is product intuition, taste and a process for making decisions.
Before product-market fit, more engineers do not speed a team up. The work is hundreds of product and design decisions and talking to users. Vibe coding multiplies the leverage of people who already have good intuition.
Money and engineers can be bought, but taste cannot. ATC, an app for listening to air traffic control, was built by a very small, AI-assisted team. Maguire says money and engineers were attainable before, while product intuition is rarer.
Maguire expects a human to pick the idea and hold conviction. Asked for app ideas, ChatGPT 5.5 gave five and two had potential. Choosing one, drilling in and committing is where the exceptional human matters.
Labs trained a point of view out of their models for safety, so the answers come out neutral. Models make obvious points as if they were discoveries, and nobody downloads an app for that.
He backs tools that break app creation into explicit decisions. Portfolio company X1 splits creation into onboarding, major features, brand and design, instead of one-shotting an app. The tool forces the creator to wrestle with trade-offs and offers recommendations rather than deciding for them.
Modular parts are easier to adjust over time. The goal is a non-technical person shipping an app that is store-ready and scalable.
Maguire argues quality is the cheapest way to lower acquisition cost. In a crowded field, a standout product is the main way to cut through the noise. Better quality drives down cost of acquisition, so a team reaches larger scale more efficiently.
Fitness apps like Ladder and Gravl differ mostly in structure and opinion, and people like that opinion. As features converge, the people behind an app and its brand matter more. His framing: "Your quality of your product will drive down your cost of acquisition."
He ignores star ratings and watches written reviews instead. Onboarding prompts collect five-star taps from people who do not care, so weak apps show 4.9. His own decade-old app, built with care, sits at 4.5.
A better signal is the ratio of written reviews to star ratings, which is harder to fake. Retained, non-churned spend is the better measure of real quality.
Cheaper building has not produced more great apps. The capital needed to start is far lower than two or five years ago, yet total consumer spend has not risen in step with the number of new apps. Competition for ad eyeballs has made everything more expensive.
Maguire says everyone who built a great app made a bunch of bad ones first. Taste is learned through bad apps, user talks and fast iteration, and the cost of iteration has fallen too.
2When Maguire says to bootstrap and when to raise venture
Maguire says raise venture only if you can name a billion-dollar exit. A founder with a few thousand dollars of MRR wanted to raise. Asked how the company sells for a billion dollars, they could only grasp at answers.
Venture is built around the power law, so investors need outliers. His warning: "Unless that is your goal and you're going to do nothing but focus on that outcome, do not raise venture capital." Bad investors make life hell, and even good ones distract.
He tells founders to bootstrap first and raise later if the market is bigger. A cash-flowing business of around $10M can reveal where a multi-billion dollar company lies. Raising then means a higher valuation, less dilution and better terms.
If the big market never appears, you still own the whole business. Curtis from Slups bootstrapped to about 12 people, reinvests every year and chose that path on purpose.
Maguire warns a bigger valuation is not a better outcome. Investors hold preferred stock, so on a $20M Series A, a $20M sale pays the investors all of it. Liquidation preferences of 2X or 3X can mean a $40M sale pays investors first and most.
He says to take anything above a 1X preference only if desperate. Such terms are rare in San Francisco in 2026 but still seen in Austin and other markets.
He matches capital strategy to the real ceiling of the business. In some markets great execution makes a company massive, and in others even perfect execution stays small. He counts years of your life as capital too, so know the best possible outcome before spending five or ten years.
Applying to YC is an obsession, but YC is tooled for $1B to $100B outcomes and helps less off that path.
Maguire thinks venture left early consumer apps for good reasons. Consumer has produced few giant outcomes. He says a $100B consumer company has yet to exist outside a handful of social products, fewer than ten.
Duolingo is worth roughly $4B to $5B, still venture-backable but harder in 2026. Venture is a transient form of capital that fades once an industry's costs fall, and nobody needs $10M to build a chess.com alternative.
He points bootstrappers at niche apps, not entrenched network effects. Disrupting a network-effect product like chess.com or Strava is nearly impossible. Strava is about 15 years old, and chess.com subscribers can stay for decades.
The open lane is niche products a small team can run to $10M a year, helped by billing infrastructure, paid user acquisition with working capital, and near-zero build cost.
3What Maguire thinks makes consumer AI investable
Maguire says only low-churn products are investable. He looks for network effects or deep personalization, where a product gets better for each user through usage alone. Health and finance fit best, like a nutritionist who knows everything you eat and your record over time.
A plant identifier app turned its skeptic into a daily user through years of stored plant data. Network effects are hard to create, and a utility often has to jumpstart the network.
He sees inference cost as a bet on timing. An AI product pays a high cost per user from the start, and investors in the labs subsidize much of it. Opus pricing has not fallen in six months, and no rival model matches it.
A top model at reasonable prices in five years is a very different business from one in 18 months. For a viral, fast-growing product, venture can bridge the gap while costs fall: "This is where venture capital is actually useful." He asks whether a feature is affordable for every user every day.
Maguire expects focused apps to survive agents and homemade software. Brand and utility keep apps alive more than features do, as with Craigslist and Coca-Cola. He calls a CEO building their own CRM instead of using Salesforce a classic venture-backed mistake that becomes a boondoggle.
People want visual, artistic experiences, not only agents talking to each other. His advice: "Let someone who's totally focused on making a thing great make that thing and then use it." The claim rests on opinion and analogy, not data.
4Maguire on financing apps that are not venture scale
Maguire says small apps with traction still need real cash. Low-end scaling needs $10K to $20K, and scaling paid ads needs a couple hundred thousand dollars. A $300K check four years ago might have cut two years of slow growth for Curtis.
Small-check funds like Tiny, NDVC and ComFund stopped. A small-check, profit-share model would not rely on a power law.
He explains why small funds struggle to compete for capital. Capital flows to the best return, and with the S&P on a generational run, treasuries and index funds are the real competition. Even a great fund might 5X in five years.
Private investments are also a hassle compared with a Robinhood or Fidelity account.
Maguire expects debt-style financing to fill the gap. RevenueCat's Daily Payouts is a factoring product that could extend to loans against current run rate. Debt caps the lender's profit but lets them capture the downside, while venture debt adds equity warrants.
His view is that a good return on capital will eventually become a product.
He points to cohort-based UA financing as a model. General Catalyst finances up to 80% of user acquisition, tracked by monthly cohort. On $10M of January spend they finance $8M, charge about 10% annualized interest, and are repaid from that cohort's earnings.
It avoids dilution and personal recourse, and a slow cohort simply takes three years to repay. Ladder used it. It is open only to larger, proven apps, and Maguire sees room for a smaller version.
5How Maguire uses and vets AI in his own work
Maguire built his own CRM and to-do list and has it self-improve. He linked both to email and has the tool evaluate and improve its own prioritizing.
He says natural-language analytics only work if you keep teaching them. A portfolio company built an internal tool anyone can query in plain language, which removes the bottleneck of analysts and engineers running SQL. The risk is garbage in, garbage out.
The tool needs ongoing effort to understand data structures: "you have to put a lot of effort into making sure it's good."
Maguire vets AI vendors for security governance, not just speed. He has seen multiple serious security incidents in the past year that he thinks would not have happened before AI. Going slow is not the answer because competitors would crush you.
He says to weigh the trade-offs internally and ask vendors how they think about governance and what their principles are.
The Bootstrapper's Path to $10M ARR Without Venture Capital – Andrew Maguire, Volo Ventures
Covers why product taste and judgment, not engineering, is now the bottleneck for great apps, what makes consumer subscription investable in 2026, and when to bootstrap versus raise venture. The takeaway is that cheap building, UA financing and tooling make a $10M indie app more reachable than ever, while venture only fits if you can name a billion-dollar outcome.
Maguire says product taste now limits how many great apps exist. Five years ago $20M could hire the best engineers, but without product intuition it was $20 million on fire. Today the cap on high-quality apps is product intuition, taste and a process for making decisions.
Before product-market fit, more engineers do not speed a team up. The work is hundreds of product and design decisions and talking to users. Vibe coding multiplies the leverage of people who already have good intuition.
Money and engineers can be bought, but taste cannot. ATC, an app for listening to air traffic control, was built by a very small, AI-assisted team. Maguire says money and engineers were attainable before, while product intuition is rarer.
Maguire expects a human to pick the idea and hold conviction. Asked for app ideas, ChatGPT 5.5 gave five and two had potential. Choosing one, drilling in and committing is where the exceptional human matters.
Labs trained a point of view out of their models for safety, so the answers come out neutral. Models make obvious points as if they were discoveries, and nobody downloads an app for that.
He backs tools that break app creation into explicit decisions. Portfolio company X1 splits creation into onboarding, major features, brand and design, instead of one-shotting an app. The tool forces the creator to wrestle with trade-offs and offers recommendations rather than deciding for them.
Modular parts are easier to adjust over time. The goal is a non-technical person shipping an app that is store-ready and scalable.
Maguire argues quality is the cheapest way to lower acquisition cost. In a crowded field, a standout product is the main way to cut through the noise. Better quality drives down cost of acquisition, so a team reaches larger scale more efficiently.
Fitness apps like Ladder and Gravl differ mostly in structure and opinion, and people like that opinion. As features converge, the people behind an app and its brand matter more. His framing: "Your quality of your product will drive down your cost of acquisition."
He ignores star ratings and watches written reviews instead. Onboarding prompts collect five-star taps from people who do not care, so weak apps show 4.9. His own decade-old app, built with care, sits at 4.5.
A better signal is the ratio of written reviews to star ratings, which is harder to fake. Retained, non-churned spend is the better measure of real quality.
Cheaper building has not produced more great apps. The capital needed to start is far lower than two or five years ago, yet total consumer spend has not risen in step with the number of new apps. Competition for ad eyeballs has made everything more expensive.
Maguire says everyone who built a great app made a bunch of bad ones first. Taste is learned through bad apps, user talks and fast iteration, and the cost of iteration has fallen too.
Maguire says raise venture only if you can name a billion-dollar exit. A founder with a few thousand dollars of MRR wanted to raise. Asked how the company sells for a billion dollars, they could only grasp at answers.
Venture is built around the power law, so investors need outliers. His warning: "Unless that is your goal and you're going to do nothing but focus on that outcome, do not raise venture capital." Bad investors make life hell, and even good ones distract.
He tells founders to bootstrap first and raise later if the market is bigger. A cash-flowing business of around $10M can reveal where a multi-billion dollar company lies. Raising then means a higher valuation, less dilution and better terms.
If the big market never appears, you still own the whole business. Curtis from Slups bootstrapped to about 12 people, reinvests every year and chose that path on purpose.
Maguire warns a bigger valuation is not a better outcome. Investors hold preferred stock, so on a $20M Series A, a $20M sale pays the investors all of it. Liquidation preferences of 2X or 3X can mean a $40M sale pays investors first and most.
He says to take anything above a 1X preference only if desperate. Such terms are rare in San Francisco in 2026 but still seen in Austin and other markets.
He matches capital strategy to the real ceiling of the business. In some markets great execution makes a company massive, and in others even perfect execution stays small. He counts years of your life as capital too, so know the best possible outcome before spending five or ten years.
Applying to YC is an obsession, but YC is tooled for $1B to $100B outcomes and helps less off that path.
Maguire thinks venture left early consumer apps for good reasons. Consumer has produced few giant outcomes. He says a $100B consumer company has yet to exist outside a handful of social products, fewer than ten.
Duolingo is worth roughly $4B to $5B, still venture-backable but harder in 2026. Venture is a transient form of capital that fades once an industry's costs fall, and nobody needs $10M to build a chess.com alternative.
He points bootstrappers at niche apps, not entrenched network effects. Disrupting a network-effect product like chess.com or Strava is nearly impossible. Strava is about 15 years old, and chess.com subscribers can stay for decades.
The open lane is niche products a small team can run to $10M a year, helped by billing infrastructure, paid user acquisition with working capital, and near-zero build cost.
Maguire says only low-churn products are investable. He looks for network effects or deep personalization, where a product gets better for each user through usage alone. Health and finance fit best, like a nutritionist who knows everything you eat and your record over time.
A plant identifier app turned its skeptic into a daily user through years of stored plant data. Network effects are hard to create, and a utility often has to jumpstart the network.
He sees inference cost as a bet on timing. An AI product pays a high cost per user from the start, and investors in the labs subsidize much of it. Opus pricing has not fallen in six months, and no rival model matches it.
A top model at reasonable prices in five years is a very different business from one in 18 months. For a viral, fast-growing product, venture can bridge the gap while costs fall: "This is where venture capital is actually useful." He asks whether a feature is affordable for every user every day.
Maguire expects focused apps to survive agents and homemade software. Brand and utility keep apps alive more than features do, as with Craigslist and Coca-Cola. He calls a CEO building their own CRM instead of using Salesforce a classic venture-backed mistake that becomes a boondoggle.
People want visual, artistic experiences, not only agents talking to each other. His advice: "Let someone who's totally focused on making a thing great make that thing and then use it." The claim rests on opinion and analogy, not data.
Maguire says small apps with traction still need real cash. Low-end scaling needs $10K to $20K, and scaling paid ads needs a couple hundred thousand dollars. A $300K check four years ago might have cut two years of slow growth for Curtis.
Small-check funds like Tiny, NDVC and ComFund stopped. A small-check, profit-share model would not rely on a power law.
He explains why small funds struggle to compete for capital. Capital flows to the best return, and with the S&P on a generational run, treasuries and index funds are the real competition. Even a great fund might 5X in five years.
Private investments are also a hassle compared with a Robinhood or Fidelity account.
Maguire expects debt-style financing to fill the gap. RevenueCat's Daily Payouts is a factoring product that could extend to loans against current run rate. Debt caps the lender's profit but lets them capture the downside, while venture debt adds equity warrants.
His view is that a good return on capital will eventually become a product.
He points to cohort-based UA financing as a model. General Catalyst finances up to 80% of user acquisition, tracked by monthly cohort. On $10M of January spend they finance $8M, charge about 10% annualized interest, and are repaid from that cohort's earnings.
It avoids dilution and personal recourse, and a slow cohort simply takes three years to repay. Ladder used it. It is open only to larger, proven apps, and Maguire sees room for a smaller version.
Maguire built his own CRM and to-do list and has it self-improve. He linked both to email and has the tool evaluate and improve its own prioritizing.
He says natural-language analytics only work if you keep teaching them. A portfolio company built an internal tool anyone can query in plain language, which removes the bottleneck of analysts and engineers running SQL. The risk is garbage in, garbage out.
The tool needs ongoing effort to understand data structures: "you have to put a lot of effort into making sure it's good."
Maguire vets AI vendors for security governance, not just speed. He has seen multiple serious security incidents in the past year that he thinks would not have happened before AI. Going slow is not the answer because competitors would crush you.
He says to weigh the trade-offs internally and ask vendors how they think about governance and what their principles are.